
Sole proprietor credit loan
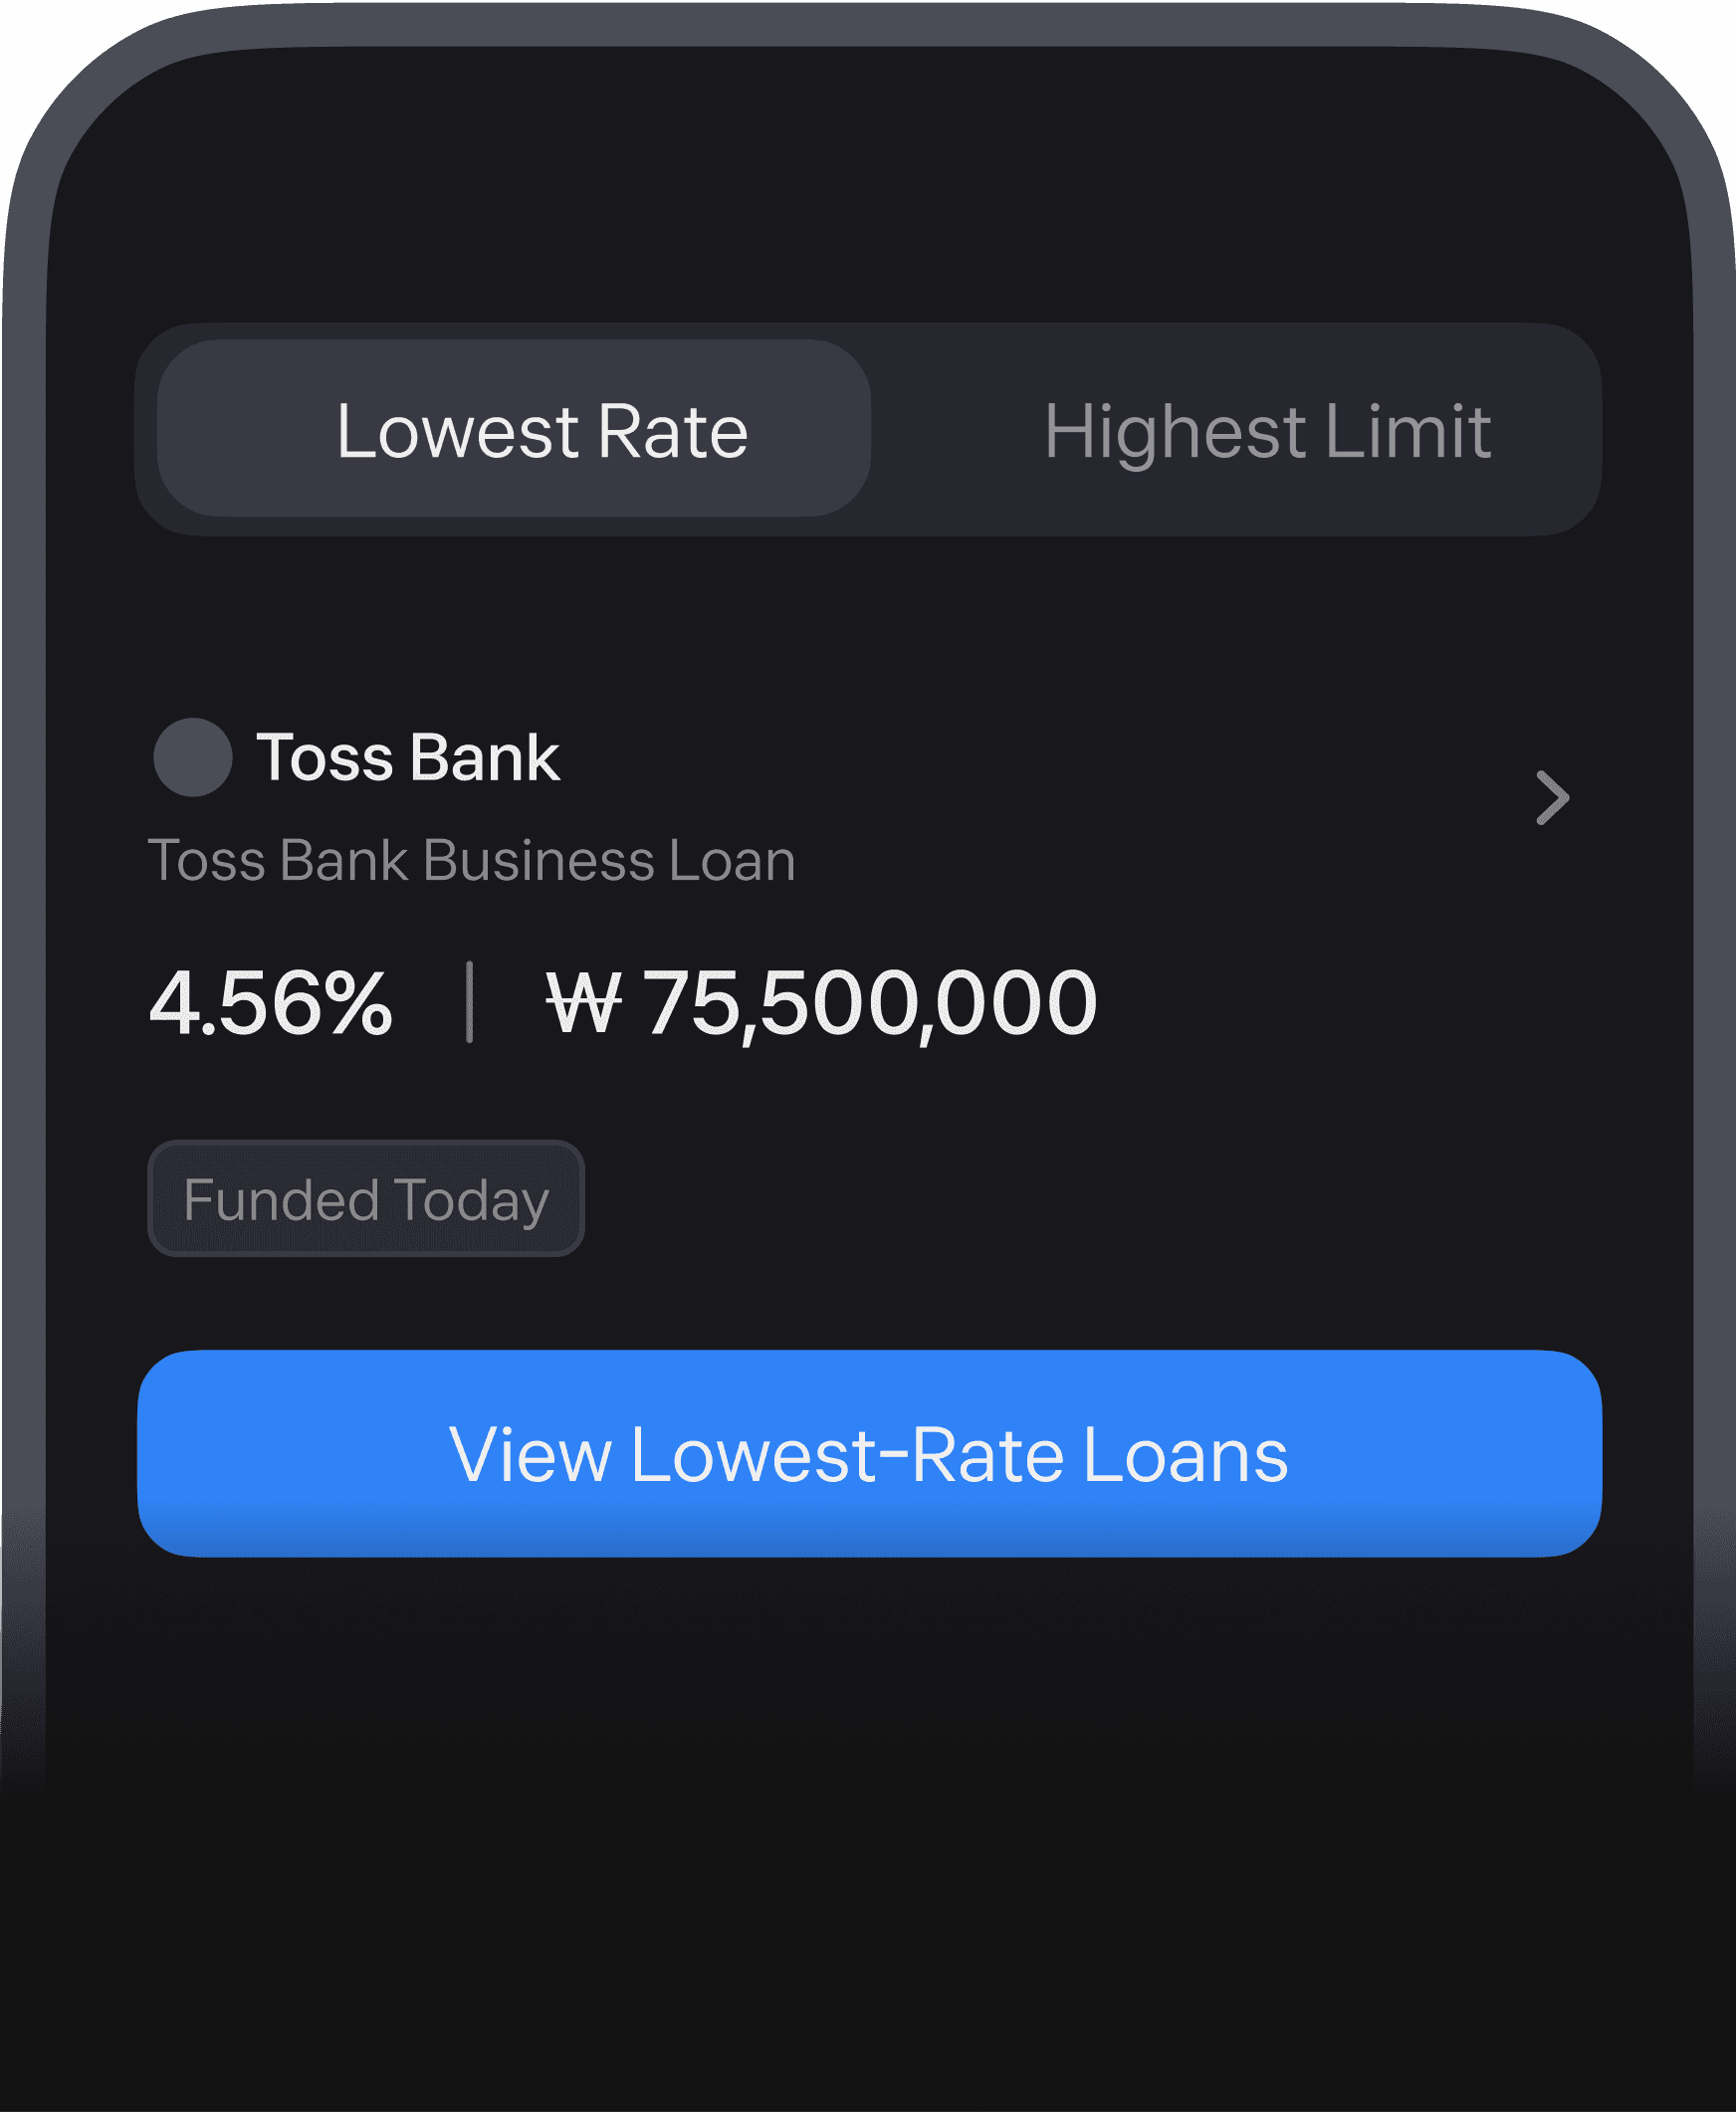
Your limit is based on factors including your credit and business information, such as sales and how long you’ve been operating. Use it for larger business expenses like rent, payroll and materials.

Guaranteed loans
Compare products from guarantee institutions, including the Korea Credit Guarantee Fund and regional credit guarantee foundations. These may offer relatively lower rates and may be available even with a lower credit score.
Business credit line
Use only what you need and pay interest only on what you use. Built for flexible access to working capital for fast-moving cash needs.
For business owners
If you have a business registration number and are actively operating, you can apply. See lower-rate options for the amount you need, up to KRW 500 million.
For licensed professionals
Access products built around your profession. Have a business registration certificate? You can apply even before opening your business.

Domestic calls
1661-7654 (24/7, 365 days a year)
International calls
+82-2-6975-9000
help@tossbank.com
Product Information
Eligibility
Sole Proprietor Guarantee Loan
Customers who can be issued a guarantee by a credit guarantee institution (Credit Guarantee Foundation, Korea Credit Guarantee Fund, Korea Trade Insurance Corporation)
- Applications are not available if the business is in a guarantee-restricted industry designated by credit guarantee institutions.
- If the credit guarantee institution is the Korea Credit Guarantee Fund or Korea Trade Insurance Corporation, joint business owners cannot apply.
Sole Proprietor Credit Loan, Sole Proprietor Credit Line
Sole proprietors with at least 1 year since the business opening date shown on the business registration certificate (or with sales records for the most recent 6 months or longer) and annual income of KRW 5 million or more
- The business period is calculated based on the opening date shown on the business registration certificate.
- Annual income is determined based on Hometax standard financial statements, income certificate, VAT tax base certificate, or VAT-exempt business revenue amount certificate for tax-exempt businesses.
Professional Business Owner Loan
Sole proprietors who have a business registration certificate, are currently operating normally or preparing to open, and hold a professional license (doctor, dentist, Korean medicine doctor, veterinarian, pharmacist, lawyer, patent attorney, tax accountant, or certified public accountant)
Common Requirements
- Sole proprietors with an active business registration number (excluding suspended or closed businesses and corporate businesses)
- Korean nationals age 19 or older
- Customers with no credit judgment information registered, such as delinquency or default information
- Customers with no history of applying for rehabilitation, bankruptcy, exemption from liability, etc.
- Customers with no overdue loans at Toss Bank and no history of causing losses to the bank
- Customers with no records related to financial fraud or other financial transaction restrictions
Loan Limit
- Limits are applied differently according to the limit calculated by the credit guarantee institution and the bank's credit evaluation system, based on personal credit, repayment ability, debt status, and other factors.
- For customers engaged in real estate rental business, the Sole Proprietor Credit Loan limit is combined with the Sole Proprietor Credit Line and capped at KRW 100 million.
- The Sole Proprietor Guarantee Loan is a product secured by a guarantee (75% to 100% of the loan amount) from a guarantee institution (Credit Guarantee Foundation, Korea Credit Guarantee Fund, Korea Trade Insurance Corporation).
- The maximum loan limit for the Sole Proprietor Guarantee Loan may differ depending on the product type.*
Loan Term and Repayment Method
Sole Proprietor Guarantee Loan
Lump-sum repayment at maturity
- Loan term: 1 year (extendable in 1-year increments up to 5 years)
- A method where you pay only interest each month first and repay the principal at the end of the loan
- For credit lines, repayment and reuse are available at any time within the loan limit.
Equal principal installment repayment
- Loan term: 4 to 7 years
- A method where you pay only interest during the grace period, then from the start of installment repayment, divide the principal into equal monthly amounts and repay it with monthly interest
- The loan term may differ depending on the repayment method and grace period of the guarantee issued by the guarantee institution (Credit Guarantee Foundation, Korea Credit Guarantee Fund, Korea Trade Insurance Corporation).
Sole Proprietor Credit Loan
Lump-sum repayment at maturity
- Loan term: 1 year (extendable in 1-year increments up to 10 years)
- A method where you pay only interest each month first and repay the principal at the end of the loan
Equal principal and interest installment repayment
- Loan term: 1 to 5 years
- A method where the loan principal and interest are divided by the loan term and repaid in equal monthly amounts
Sole Proprietor Credit Line
Lump-sum repayment at maturity
- Loan term: 1 year (extendable in 1-year increments up to 10 years)
- A method where you pay only interest each month first and repay the principal at the end of the loan
Professional Business Owner Loan
Lump-sum repayment at maturity
- Loan term: 1 year (extendable in 1-year increments up to 10 years)
- A method where you pay only interest each month first and repay the principal at the end of the loan
Costs Borne by Customer
- Stamp tax is a tax paid when entering into a loan transaction agreement. KRW 70,000 (loan amount over KRW 50 million) or KRW 150,000 (loan amount over KRW 100 million) may be incurred, and the customer bears 50% of this amount.
- The guarantee fee is calculated on the guarantee principal (for Sole Proprietor Guarantee Loans, 75% to 100% of the loan amount depending on the guarantee product of the credit guarantee institution).
- The guarantee fee rate for Sole Proprietor Guarantee Loans may differ depending on the product type.
- When taking out a Credit Guarantee Foundation guarantee loan, the guarantee fee for the loan term (1 to 7 years) is paid to the Credit Guarantee Foundation in a lump sum.
- When taking out a Korea Credit Guarantee Fund guarantee loan, after paying the guarantee fee for the first year at loan execution, the fee is paid annually in installments (4 times). The guarantee fee rate applied at the time of new loan execution may be raised at the installment payment point according to Korea Credit Guarantee Fund regulations.
- When taking out a Korea Trade Insurance Corporation guarantee loan, the guarantee fee for the loan term (4 years) is paid to the Korea Trade Insurance Corporation in a lump sum.
Eligibility Verification Documents
Business registration certificate, income certificate, VAT tax base certificate or VAT-exempt business revenue amount certificate, standard financial statements certificate, VAT return, purchase/sales tax invoice summary by counterparty, resident registration certificate/extract, national tax payment certificate, local tax payment certificate, certificate of full payment of the four major social insurance premiums, health insurance premium payment confirmation, professional qualification certificate (license), etc.
- After identity verification through a Toss Certificate, etc., documents can be submitted in the mobile app through Public MyData and scraping.
- For Credit Guarantee Foundation guarantee loans, a lease agreement is required for the address with a lease contract.
Available Application Hours
- The available application hours for Opportunity Guarantee Loans are weekdays 09:00 to 16:00.
- The available application hours for Seoul Safe Credit Line are weekdays 09:00 to 18:00.
- The loan execution hours for Sole Proprietor Credit Loans are daily 06:00 to 22:00.
- The loan execution hours for Credit Guarantee Foundation and Korea Trade Insurance Corporation guarantee loans are weekdays (excluding holidays) 09:00 to 16:00, and the loan execution hours for Korea Credit Guarantee Fund guarantee loans are weekdays (excluding holidays) 09:00 to 15:00.
Interest Rate Information
Sole Proprietor Guarantee Loan
Sole Proprietor Credit Loan
Sole Proprietor Credit Line
Professional Business Owner Loan
- Loan interest rate = base rate + customer-specific spread - interest subsidy rate
- For Sole Proprietor Credit Loan, Professional Business Owner Loan, and Korea Credit Guarantee Fund guarantee loans, you can choose from the 3-month financial bond (repricing cycle: 3 months), 6-month financial bond (repricing cycle: 6 months), or 12-month financial bond (repricing cycle: 12 months). The loan interest rate changes in line with the base rate on the corresponding date of each repricing cycle for the selected base rate. Even after maturity, the repricing cycle continues, so the loan interest rate changes in line with the base rate on that date.
- For Credit Guarantee Foundation guarantee loans, the base rate is the CD-linked loan rate (91-day), and the loan interest rate changes in line with the base rate on the corresponding date of each repricing cycle, or the closing rate on the Thursday before the corresponding date of each repricing cycle (or the previous business day if that day is a holiday). Even after maturity, the repricing cycle continues, so the loan interest rate changes in line with the base rate on that date.
- For Korea Trade Insurance Corporation guarantee loans, the base rate is the CD-linked loan rate (91-day), and the loan interest rate changes in line with the base rate on the corresponding date of each repricing cycle. Even after maturity, the repricing cycle continues, so the loan interest rate changes in line with the base rate on that date.
- Customer-specific spreads are applied differently based on the bank's internal credit grade, loan term, and other factors.
- The interest subsidy rate applies only to products with an interest support agreement and may change depending on the guarantee review result of the credit guarantee institution.
- Interest support is provided by the government or local governments, and the interest support rate may not apply depending on the circumstances of the credit guarantee institution.
- Please contact the regional credit guarantee foundation to check whether an interest support guarantee can be issued.
- The application period of the interest subsidy rate may differ from the total loan term.
- The interest subsidy rate is excluded if a reason for discontinuation occurs, such as using the loan funds for purposes other than the stated purpose, business suspension or closure, default, moving the business to another city or province, overdue loan principal or interest, or expiration of the interest subsidy period.
Overdue Interest Rate
If an unpaid amount occurs as of the monthly payment date, overdue interest accrues as follows.
- The maximum overdue interest rate is 15% per year. If the loan interest rate is 15% per year or higher, the loan interest rate + 2% per year applies.
- For Sole Proprietor Credit Loans and Professional Business Owner Loans, if the unpaid amount is not repaid for 1 month or more while overdue, overdue interest accrues on the entire loan amount at the point 1 month has passed (for principal and interest installment repayment, when 2 or more payments are overdue).
- If there is a grace period, during the grace period, if the unpaid amount is not repaid for 1 month or more while overdue, overdue interest accrues on the entire loan amount at the point 1 month has passed (during the installment repayment period, when 2 or more payments are overdue).
- More details can be found in the terms and product explanation.
Other Information
Interest Payment Method
- When you take out a new loan, you can choose your automatic transfer date (payment date), and payments will be made on that date every month. As long as the payment date has not already passed, you can change the payment date during the loan term.
※ If you choose a date other than the loan start date, payment may be made on the next occurrence of that date. Please check the first payment date shown during your loan application.
- The Sole Proprietor Guarantee Loan is a policy loan product. The automatic transfer date (payment date) is set based on the loan execution date, and payment is made on that date every month. The automatic transfer date (payment date) cannot be changed during the loan term.
- Interest is calculated by multiplying the loan balance from the previous interest payment date (or loan start date) through the day before the current interest payment date by the loan interest rate.
- Loan interest is automatically withdrawn from your automatic transfer account on the monthly interest payment date (or the next business day if it falls on a holiday). If the available balance is insufficient, overdue interest may accrue. You can deposit the repayment funds on that day or make a repayment directly in the app, including on holidays.
Important Notes
- Depending on the bank's review standards, credit evaluation results, and other factors, your loan may be declined or restricted, and loan terms such as the loan limit and interest rate may vary.
- When you apply for a loan, your credit inquiry history is provided to credit information companies, and depending on your credit status, this may affect loan reviews by other financial institutions. If the loan is executed, your credit score may decrease depending on your debt level, credit status, and other factors.
- If you are subject to a post-check on use of funds for purposes other than the stated purpose, the loan can be executed only after you provide evidence of the use of funds after the loan agreement. If needed, we may request documents to verify how the loan funds were used. The use of the loan funds must be fully verified within 6 months. If you do not provide proof of use within the deadline, you may lose the benefit of the loan term and be required to repay the full loan amount.
- If the loan amount is excessive relative to your repayment ability, your personal credit score may decrease. A decrease in your personal credit score may result in disadvantages in financial transactions.
- For loans repaid in a lump sum at maturity, the loan agreement term is 1 year. To extend the loan term, you must apply for an extension through the app before maturity each year. If you do not repay the loan without extending the loan term, overdue interest will apply to the outstanding balance, and registration of overdue information may result in disadvantages in financial transactions. For Sole Proprietor Guarantee Loans repaid in a lump sum at maturity, an additional extension through the guarantee institution is required before maturity.
- Depending on the result of the term extension review based on your personal circumstances and creditworthiness, you may be required to repay part of the loan. If the extension is denied, you must repay the outstanding loan balance and all unpaid interest.
- If the loan remains unpaid after maturity, overdue interest will apply to the outstanding balance, and registration of overdue information may result in disadvantages in credit transactions.
- If delinquency continues for a certain period, you may become obligated to repay all principal and interest before the end of the agreed term. Depending on the delinquency period, you may be registered as having “overdue information, etc.” under the Credit Information Use and Protection Act and the General Credit Information Management Rules, which may result in disadvantages in financial transactions.
- General financial consumers have the right to receive an explanation of this loan product under Article 19(1) of the Financial Consumer Protection Act.
- Please read the product explanation and terms before entering into the agreement.
Right to Request an Interest Rate Reduction
- For loans where interest rates are applied differently based on the bank's personal credit evaluation results, you may request an interest rate reduction in the mobile app if there is a significant change in your credit status, such as a job change, increased income, reduced debt, or higher credit score.
- However, an interest rate reduction may not be granted depending on the bank's internal policy or credit evaluation results.
- The Sole Proprietor Guarantee Loan is excluded from interest rate reduction requests when the loan is executed with a full guarantee from a guarantee institution, such as the Korea Credit Guarantee Foundation, Korea Credit Guarantee Fund, or Korea Trade Insurance Corporation.
Reasons for Requesting an Interest Rate Reduction
Increase in credit score
- If your personal credit score from a credit rating agency has increased: because credit rating agencies' personal credit information is mainly used in the bank's credit evaluation, an increase in your personal credit score from a credit rating agency may improve the bank's internal credit rating.
Increase in income and assets
- If your income and assets have increased: increases in income and assets can positively affect the bank's internal credit rating by contributing to reduced loans, resolved delinquency, or increased financial assets.
Right to Withdraw from the Loan Agreement
- The right to withdraw from a loan agreement refers to the right to withdraw from the loan agreement during the cooling-off period for the loan agreement.
- You may apply within 14 days from the loan execution date (or the next business day if it falls on a holiday), and you must return the loan principal and interest as well as costs borne by the bank, including costs paid to third parties in relation to the loan agreement.
- When you withdraw from the loan agreement, the bank immediately requests deletion of the loan information from external credit rating agencies and credit information concentration institutions, and the deletion is reflected within 5 business days.
- Once withdrawal from the loan agreement is complete, it cannot be canceled.
Right to Terminate an Unlawful Agreement
- The right to terminate an unlawful agreement refers to the right to terminate the agreement if Toss Bank entered into the loan agreement in violation of its obligations under the Financial Consumer Protection Act, including suitability, appropriateness, and duty of explanation, or through unfair trade practices or improper solicitation.
- You may request termination of the loan agreement in writing within 1 year from the date you became aware of the legal violation, provided that this must be within 5 years from the agreement date.
- The bank will notify you of the result and reason within 10 days from the date it receives the termination request.
- For more details, please refer to the terms and product explanation.
- This notice is provided through procedures under the Financial Consumer Protection Act and Toss Bank's internal control standards.
Product Explanation and Terms
Corporate Loan Product Explanation
General Terms and Conditions for Bank Credit Transactions (Corporate)
Loan Transaction Agreement (Corporate)
Additional Loan Transaction Agreement (Corporate)
Additional Loan Transaction Agreement (Interest Subsidy Loan)
Credit Guarantee Agreement (Individual Transaction, Non-face-to-face) (Korea Credit Guarantee Fund)
Reviewed and approved by Toss Bank Compliance: No. 2026-2203 (July 21, 2026 – July 20, 2027) / Start date: July 21, 2026 / End date: July 20, 2027